researcher mapping multiperiod decision trees

Built by researchers

You are not reading recycled blog posts. Every framework here started as a working paper, tested against real market data, then refined through peer review before it reached you.

Designed for practitioners

You need tools that survive contact with actual portfolios. We strip out the elegant assumptions that break the moment a dividend arrives late or a correlation jumps.

Ambiguity, not just risk

You already know variance. We teach you to model what happens when you do not even trust the variance itself — the deeper layer of uncertainty that standard textbooks skip.

Multiperiod by default

You do not live in a single-period world. Your decisions today reshape the menu of choices tomorrow, so our models treat time as a structure, not an afterthought.
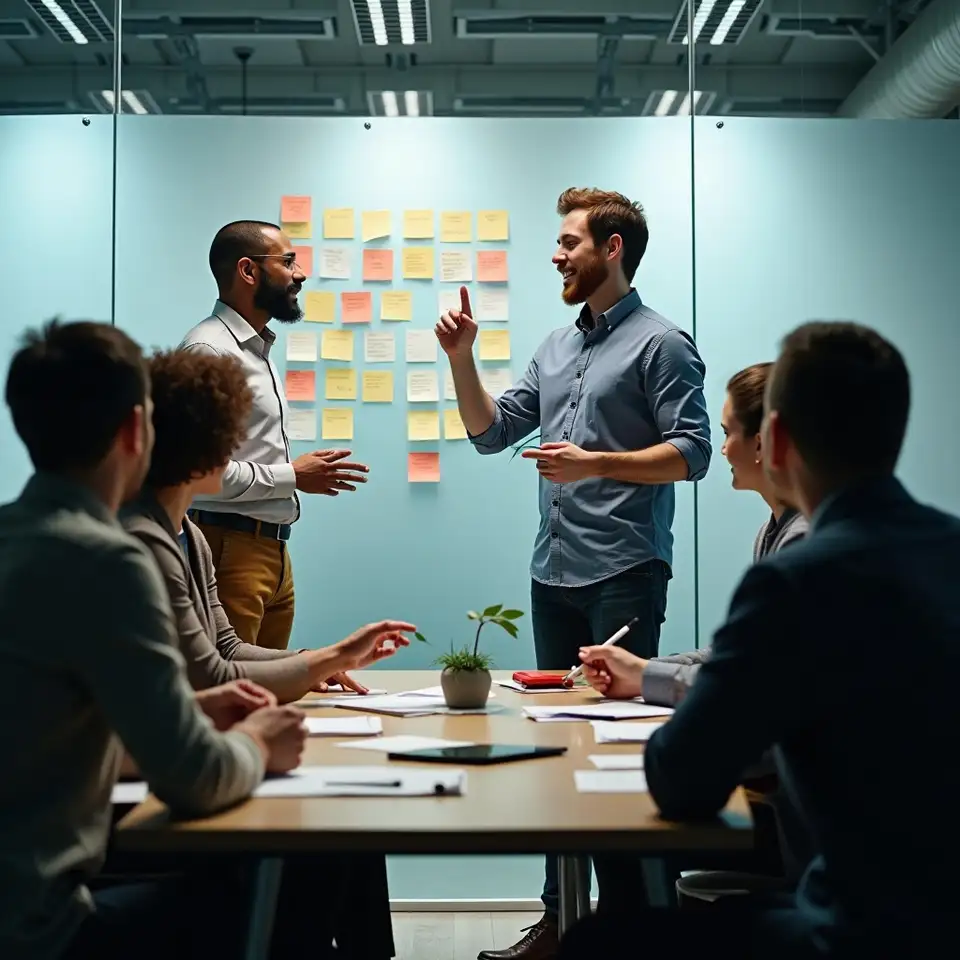
team debating model assumptions

From journal to judgement

You get the intuition first, then the proof. We translate formal theorems into decision heuristics you can stress-test in a spreadsheet before committing capital.

No black boxes

You see every assumption exposed. If a model requires you to believe something absurd, we say so loudly, then show you how to relax it.

Community of sceptics

You join peers who ask the same awkward questions you do. We host open forums where the best critique comes from the person sitting next to you.
open journal with annotated equations

Evidence over eloquence

You deserve claims you can verify. We publish our data, cite our sources, and welcome the replication that keeps us honest.

We start where certainty ends

Team

The people behind the models
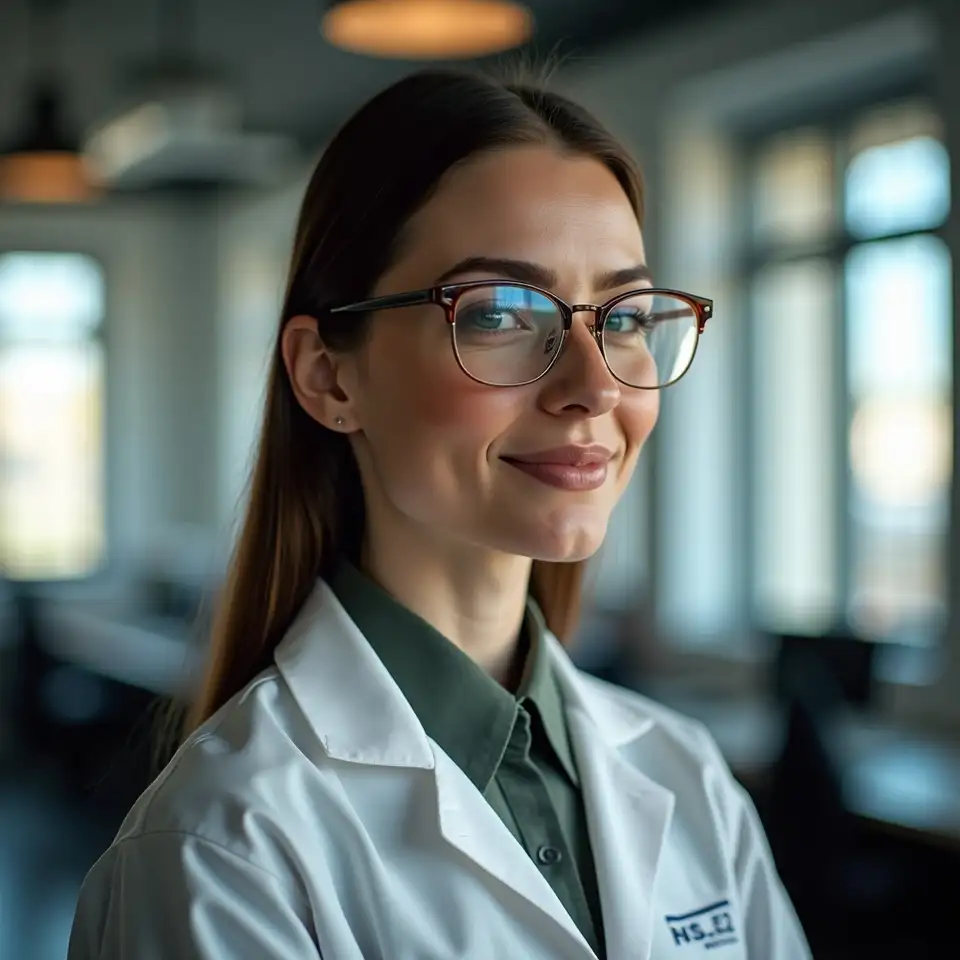
Dr. Elena Voss portrait

Dr. Elena Voss

Lead Researcher

1
Decision Theory

Doctor of Philosophy University of Auckland

Reserve Bank

Skills

Modelling
Research
Teaching

Methods

Robust Control
Bayesian Updating
Dynamic Programming

Credentials

Financial Risk Manager
Chartered Analyst

Pioneered robust multiperiod frameworks for institutional ambiguity modelling.

Elena spent a decade watching elegant models fail in live trading rooms. She now leads the research programme, insisting every theorem pass a real-data stress test before publication.

Marcus Chen portrait

Marcus Chen

Quantitative Lead

2
Computational Finance

Master of Science Victoria University

Data Science Lab

Skills

Programming
Statistics
Visualization

Methods

Monte Carlo Simulation
Scenario Analysis
Stochastic Calculus

Credentials

Machine Learning Specialist
Quantitative Methods

Develops computational tools that translate abstract theorems into working portfolio diagnostics.

Marcus bridges the gap between whiteboard mathematics and production code. He builds the engines that let you test ambiguity-averse rules against historical market behaviour.

Aroha Te Kanawa portrait

Aroha Te Kanawa

Applied Researcher

3
Empirical Finance

Master of Commerce University of Canterbury

Economic Consultancy

Skills

Econometrics
Data Cleaning
Reporting

Methods

Panel Regression
Event Studies
Bootstrap Methods

Credentials

Statistical Analysis
Data Ethics

Tests theoretical models against Australasian market data, identifying where assumptions meet reality.

Aroha runs the empirical validation programme. Her job is to find the edge cases where theory breaks, then feed those fractures back into the next model revision.

James Whitmore portrait

James Whitmore

Operations Director

4
Regulatory Compliance

Bachelor of Laws University of Otago

Legal Practice

Skills

Governance
Communication
Planning

Methods

Risk Assessment
Process Design
Quality Assurance

Credentials

Project Management
Compliance Officer

Ensures research outputs reach practitioners with clarity, accuracy, and appropriate context.

James keeps the research honest and the delivery timely. He oversees the checks that ensure every claim we publish withstands both academic and regulatory scrutiny.

Our path

5 records
2017
3

First publication

A working paper on recursive ambiguity aversion in multiperiod settings attracted attention from three central banks and a quiet hedge fund in Singapore.

001
2019
12

Pilot programme

We ran a closed trial with twelve institutional analysts, refining our models against their live portfolio decisions and documenting every failure mode.

002
2021
1

Curriculum launch

The first structured programme combined formal proofs with spreadsheet-based exercises, designed for professionals who needed usable tools, not academic credentials.

003
2023
1

Platform release

We opened the digital workspace where subscribers build, test, and share their own ambiguity-averse decision rules using our computational engine.

004
2025
4

Global partnerships

Research collaborations now span four continents, with joint projects exploring how cultural differences in probability judgement affect multiperiod choices.

005

Recognition for rigorous inquiry

Independent validation from academic societies, industry panels, and journals that subject claims to replication.

Year 2019

Best Paper Award

Recognised for advancing recursive utility models under Knightian uncertainty in continuous time.

Year 2021

Research Excellence

Honoured for methodological innovation in empirical testing of ambiguity-averse portfolio rules.

Year 2022

Citation Laureate

Named among the most-cited working papers in decision theory published that calendar year.

Year 2024

Industry Collaboration

Awarded for the most impactful academic-practitioner partnership in financial modelling.

Year 2025

Open Science Prize

Celebrated for publishing full replication datasets alongside every peer-reviewed article.